Case Background
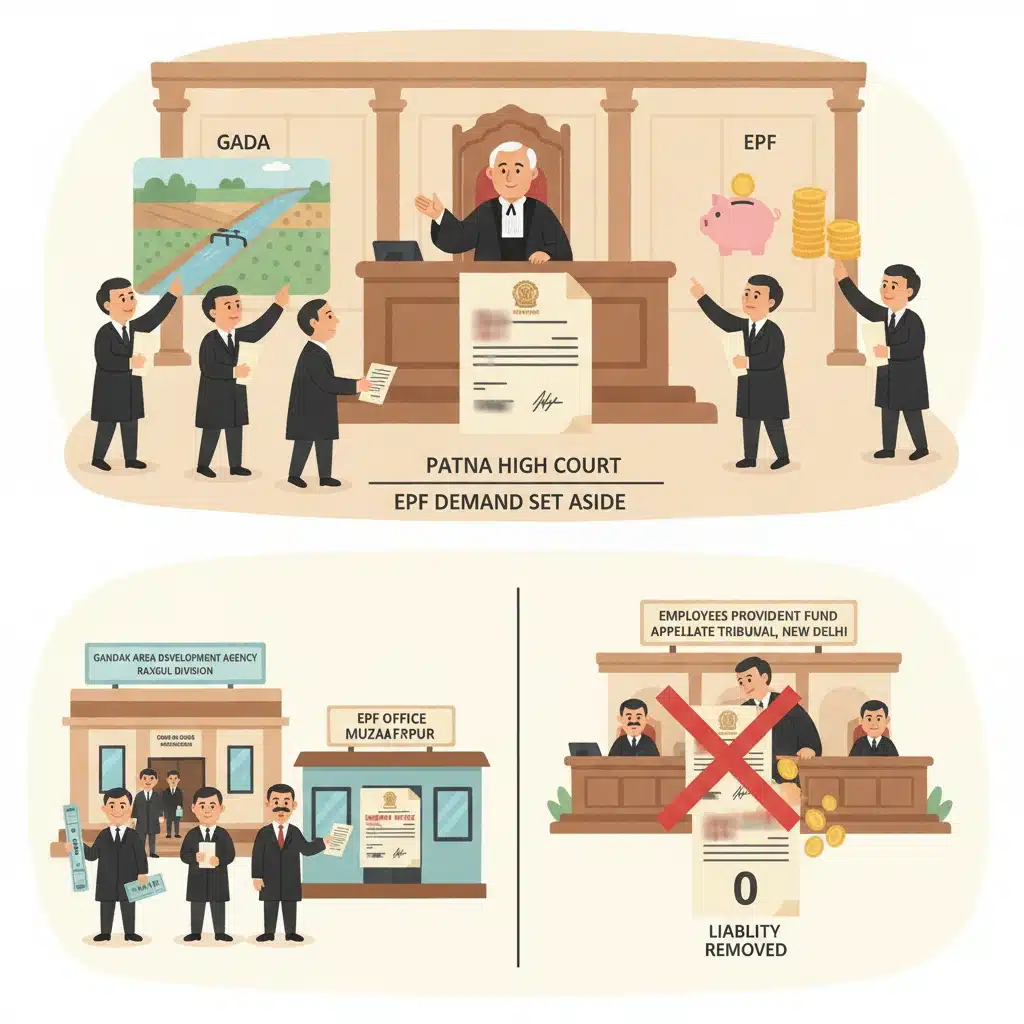
The dispute started when the Assistant Provident Fund Commissioner, Muzaffarpur, passed an order under Section 7A of the Employees’ Provident Funds and Miscellaneous Provisions Act, 1952. By this order, the authority fixed “entire outstanding dues” of Rs. 57,96,695/- against M/S Gandak Area Development Agency (GADA), treating its Planning and Investigation Division at Raxaul as a separate establishment covered by the EPF & MP Act.
The Assistant Provident Fund Commissioner treated the Raxaul division as an independent establishment under Section 2(a) of the EPF & MP Act with effect from 01.04.1982. A separate PF code was allotted, and GADA was directed to pay employees’ provident fund contributions accordingly.
GADA challenged this order before the Employees Provident Fund Appellate Tribunal, New Delhi in ATA No. 681(3) of 2006. The Tribunal set aside the Section 7A order and held that the organization was exempted from making such payments.
The Central Board of Trustees, EPF, through the Assistant Provident Fund Commissioner, then approached the Patna High Court by filing Civil Writ Jurisdiction Case No. 16336 of 2010. By order dated 24.11.2009, the learned Single Judge quashed the Tribunal’s decision and restored the Section 7A order, mainly on the ground that there was no formal exemption notification from the Central Government under Section 16 of the EPF & MP Act.
Aggrieved, GADA filed Letters Patent Appeal No. 204 of 2019 before a Division Bench of the Patna High Court. This appeal led to the present judgment dated 15.11.2022.
What the Court Examined and Decided
The Division Bench heard arguments from both sides. On behalf of GADA, it was explained that the agency was constituted under Section 3 of the Bihar Agriculture and Rural Area Development Agency Ordinance, 1974 as an independent agency and a body corporate under Section 3(1)(c). The agency was created for various districts in Bihar.
The Court noted from the record that GADA was initially under the financial control of the Agriculture Department of the State Government and later came under the Water Resources Department, which is presently the controlling department.
GADA’s specific stand was that its Board of Directors, Muzaffarpur, had approved Employees Contributory Provident Fund Regulation, 1978. This regulation was implemented in the organisation with effect from 01.04.1979, with the consent of its employees. Since then, Contributory Provident Fund (CPF) had been in force in GADA, Muzaffarpur.
Under this arrangement, contributory provident fund amounts were deposited in a nationalised bank in the individual accounts of employees. These amounts were pledged in the name of the Drawing and Disbursing Officer of the agency and were paid to employees upon superannuation. The Court recorded that some employees had already retired and received their dues under this scheme.
The litigation in this appeal related specifically to the Planning and Investigation Division of Raxaul. Counsel for GADA informed the Court that the agency operates in two circles and that decisions and rules framed at the agency level apply equally to all circles, divisions and sub-divisions. These units do not have separate, independent legal identities. Therefore, the benefits and liabilities of GADA as a whole extend to all such sub-units.
The Division Bench also noted from the records that GADA was a statutory agency associated with a Government department. As such, it acted under directions of the State Government and could not avoid those directions. Since GADA was created under a statute framed by the Legislature and controlled by a Government department, employees in all its units received equal facilities.
On this basis, GADA argued that none of its units, including the Raxaul division, were liable to pay EPF contributions because the exemptions available under Section 16(1)(a), (b) and (c) of the EPF & MP Act applied “proprio vigore” (by their own force) to such government-connected statutory bodies.
The Court referred to correspondence on record between the Assistant Provident Fund Commissioner, Muzaffarpur and the Secretary of GADA. GADA claimed it had supplied detailed information with supporting evidence, but the Assistant Provident Fund Commissioner allegedly ignored these materials and still treated the Raxaul division as an independent establishment covered by the Act from 01.04.1982.
This treatment led to allotment of a separate PF code and the demand for contributions which the Tribunal later set aside.
The learned Single Judge, however, had taken the view that under Section 16 of the EPF & MP Act, GADA could not claim exemption in the absence of a specific exemption notification by the Central Government, either prospective or retrospective, issued in the Official Gazette. Relying on this understanding, the Single Judge restored the Assistant Provident Fund Commissioner’s demand.
In appeal, Mr. Jha for GADA invited the Division Bench’s attention to Sections 16(a), 16(1)(b) and (c), 16A and 17 of the EPF & MP Act, 1952. He submitted that GADA fell within categories (b) and (c) of Section 16(1), for which no separate declaration of exemption is required. In his submission, Section 17 only deals with further exemptions for establishments which do not already fall within the automatic exemptions of Section 16(1)(a) to (c).
Section 17, as noticed by the Court, empowers the appropriate Government to grant exemption by notification, subject to conditions. This power can be used when, in the opinion of the Government, the organisation’s own provident fund rules or benefit schemes are not less favourable than those under the EPF Act or related schemes. Such exemption requires consultation with the Central Board, and certain Act provisions, including Sections 6, 7A, 8 and 14B, continue to apply even to exempted establishments.
The Bench also referred to Section 16A, introduced in 1988, which permits the Central Government, on application by an employer with 100 or more employees, to authorise the employer to maintain a provident fund in relation to the establishment, subject to terms and conditions. This authorisation may be cancelled if the employer breaches conditions or commits an offence under the Act within three years preceding the authorisation.
Mr. Jha argued that, in this legal framework, once the State Government had applied its Contributory Provident Fund Scheme to GADA and its sub-divisions, including Raxaul, GADA stood exempt from any further EPF contribution without needing a separate exemption under Section 17. According to him, the Single Judge had not properly considered this aspect while interfering with the Tribunal’s order.
On the other hand, counsel for the EPF authorities, Mr. Jay Prakash Verma, submitted that employees of GADA were still not receiving the benefits to which they were entitled. The judgment records this submission but does not detail specific instances.
The Division Bench also took note of later developments placed on record. With effect from 01.06.2016, the post of Area Development Commissioner-cum-Chairman, GADA, Muzaffarpur, had been abolished. The Superintending Engineer, Headquarters, Muzaffarpur, was made head of GADA, Muzaffarpur. Further, the Bihar Agriculture Rural Area Development Act, 1978 was repealed by Act 6 of 2018 with effect from 01.07.2017. As a result, command agencies under the 1978 Act were abolished, and employees of all four command agencies became employees of the Water and Land Management Institute (WALMI), Khagaul, Patna, which now controls all command areas.
After examining the record and submissions, the Division Bench concluded that the Single Judge had interfered with the Tribunal’s order on what it described as an “inchoate set of facts.” The Tribunal had found that GADA was exempt from EPF contributions, considering the existing State CPF scheme and the status of the organisation. In contrast, the Single Judge restored the Section 7A order solely on the narrow ground of absence of an explicit Central Government exemption notification without adequately addressing the statutory position argued under Section 16.
The Division Bench held that, in these circumstances, it was not proper to treat the Raxaul circle of GADA, Muzaffarpur as a separate entity required to make EPF contributions as if the exemption did not apply. Accordingly, the Court set aside the Single Judge’s order and restored the Tribunal’s order which had nullified the demand of Rs. 57,96,695/-.
However, the Court also addressed the concern raised by the EPF authorities about possible non-availability of benefits to employees. It observed that, if the EPFO genuinely believes that the organisation’s employees are not receiving benefits, nothing prevents it from removing GADA from the list of exempted organisations. For this, the EPFO must undertake necessary and separate proceedings. Should such proceedings be initiated in future against GADA, Muzaffarpur, they must be carried to their logical conclusion on the basis of the charges levelled.
Finally, the Division Bench allowed the Letters Patent Appeal, set aside the Single Judge’s judgment, and restored the Tribunal’s order.
Why This Judgment Matters
This decision is important for government-linked bodies and their staff in Bihar and elsewhere. It shows that when a statutory agency already runs a recognised Contributory Provident Fund scheme for its employees, authorities cannot casually treat one division as a separate establishment and raise heavy EPF demands without properly considering the legal exemptions under Section 16 of the EPF & MP Act.
For employees, the judgment confirms that courts will take note of existing provident fund arrangements, such as State CPF schemes, and will not automatically burden their organisation with double liability unless the law clearly requires it. At the same time, the Court has kept the door open for the EPF authorities to act, through proper proceedings, if employees are not actually getting the benefits promised under such schemes.
Practically, the judgment gives guidance on how disputes between EPFO and government-controlled agencies should be handled: by careful examination of statutory status, applicable schemes, and proper exemption procedures, rather than by assumptions about separate establishments.
Legal Issues and Answers
- Issue: Could the Planning and Investigation Division at Raxaul of GADA, Muzaffarpur be treated as an independent establishment liable to pay EPF dues of Rs. 57,96,695/- despite GADA being under a State Contributory Provident Fund scheme?
Answer: No. The Patna High Court held that, on the facts and statutory framework, the Raxaul division could not be so treated, and it restored the Tribunal’s order cancelling the EPF demand. - Issue: Was the absence of a specific Central Government exemption notification under Section 16 sufficient ground to deny exemption to GADA?
Answer: No. The Court found that the Single Judge had relied on an incomplete appreciation of facts and law and that the agency’s coverage under State CPF regulations and its statutory, government-linked character had not been properly considered. - Issue: What remedy remains if employees of such an exempted organisation are allegedly not receiving due benefits?
Answer: The EPFO may initiate separate proceedings to remove the organisation from the exempted list or otherwise act in accordance with law, and such proceedings must be taken to their logical conclusion.
Cases Cited by the Court
- No previous judicial decisions are cited or relied upon in the text of this judgment.
Case Details
Case Number: Letters Patent Appeal No. 204 of 2019 in Civil Writ Jurisdiction Case No. 16336 of 2010
Case Title: M/S Gandak Area Development Agency through its Area Development Commissioner and Chairman, Combined Building, Court Compound, Muzaffarpur v. Central Board of Trustees, EPF through the Assistant Provident Fund Commissioner, Employees Provident Fund Organization, New Vakalathkhana Building, Court Compound, Muzaffarpur
Coram: Hon’ble Mr. Justice Ashutosh Kumar and Hon’ble Mr. Justice Nawneet Kumar Pandey
Date of Judgment: 15.11.2022
Citation: 2022(4) PLJR 861
Advocates: For the appellant (GADA): Mr. Satish Chandra Jha No. 3, Advocate. For the respondent (Central Board of Trustees, EPF): Mr. Jai Prakash Verma, Advocate.
Nature of the Case: Letters Patent Appeal against a Single Judge’s order in a writ petition arising from an order under Section 7A of the EPF & MP Act and a decision of the Employees Provident Fund Appellate Tribunal.
Link to Full Judgment: https://patnahighcourt.gov.in/viewjudgment/MyMyMDQjMjAxOSMxI04=-PCwoxtl5Zas=
If you found this explanation helpful and wish to stay informed about how legal developments may affect your rights in Bihar, you may consider following Samvida Law Associates for more updates.