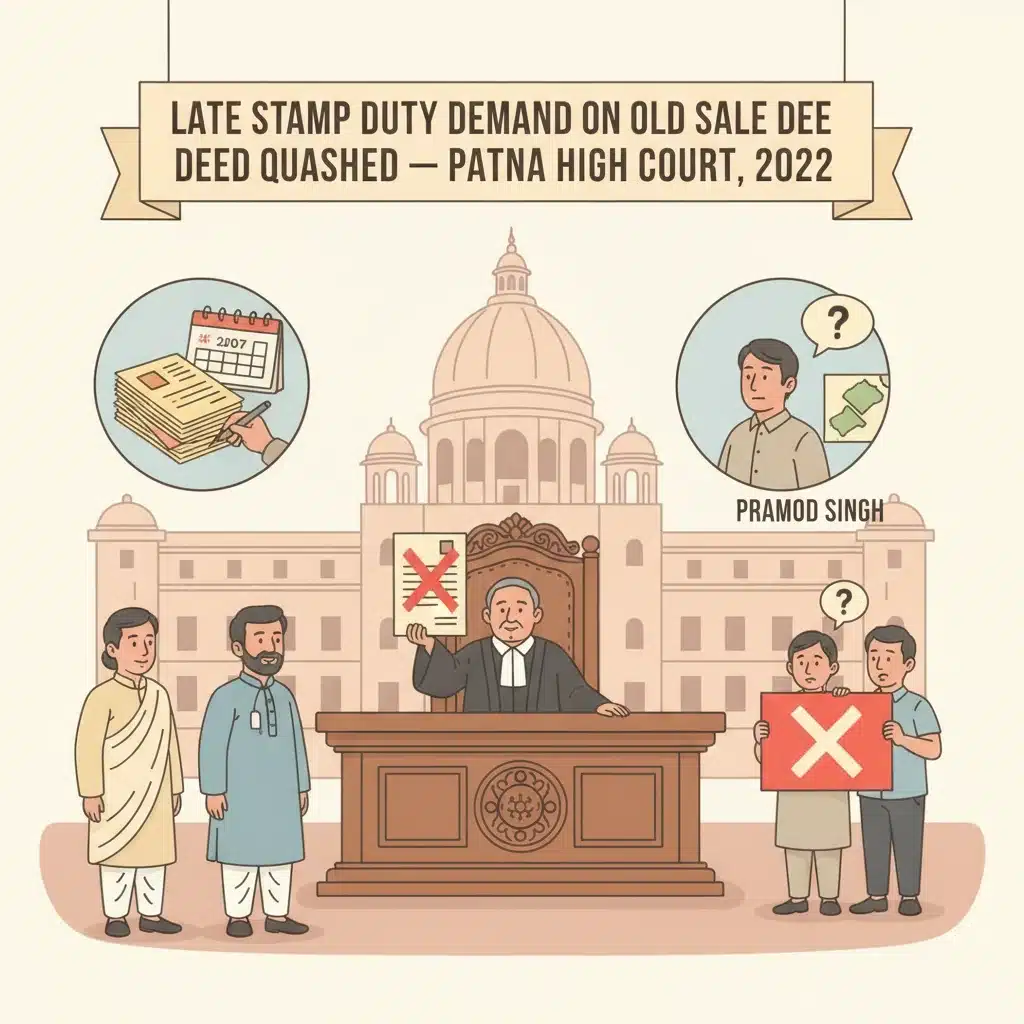
The Patna High Court held that such a delayed reference and revision of stamp duty was illegal under Section 47-A of the Indian Stamp Act, 1899.
The Court cancelled both the higher authority’s order and the Sub-Registrar’s demand notice.
No further recovery can be made from the buyer in this matter.
Case Background
The case arose from a land purchase made in the year 2007 in West Champaran district.
On 9.10.2007, the petitioner bought 36.5 decimals of land, recorded as agricultural land, from one Kedar Prasad. The land was in Khata No. 536/1222, Khesra No. 2130.
A registered sale deed bearing No. 15351 was executed on 10.10.2007. The agreed sale consideration was Rs. 2,62,000/-. The petitioner paid stamp duty of Rs. 21,160/-, calculated as per the stamp duty rate applicable in 2007.
The District Sub Registrar, Bettiah (Respondent No. 5), registered the deed and handed over the registered document to the petitioner. For several years, no objection was raised by the registration authorities.
Much later, in 2014, a private person lodged a written complaint before the Sub-Registrar alleging that the land was not agricultural but residential in nature. This triggered a fresh inquiry by the registration authorities, long after the sale deed had been registered.
What the Court Examined and Decided
The complaint made in 2014 claimed that the land purchased by the petitioner was residential, not agricultural. Acting on this complaint, the Sub-Registrar (Respondent No. 5) initiated an enquiry.
After holding the enquiry, the Sub-Registrar came to the conclusion that the land was residential. On that basis, he valued the land at Rs. 9,37,500/-, applying the Minimum Value Register (MVR) rate for residential land.
He calculated that stamp duty of Rs. 75,000/- ought to have been paid on this higher value. Considering that only Rs. 21,160/- had been paid earlier, he treated the difference as deficit stamp duty.
On 21.1.2015, the Sub-Registrar referred the matter to the Assistant Inspector General of Registration, Tirhut Division, Muzaffarpur (Respondent No. 3), invoking Section 47(A)(1) of the Indian Stamp Act, 1899.
The Assistant Inspector General registered Stamp Case No. 266/2014-2015. On 18.1.2016, he issued a notice to the petitioner under Section 47(A) of the Act, calling upon her to show cause regarding the alleged deficit stamp duty.
The petitioner appeared before Respondent No. 3 and filed her objection. Despite her objection, Respondent No. 3 passed an order dated 27.4.2017 upholding the Sub-Registrar’s reference and directed the petitioner to pay additional stamp duty.
According to the main judgment narrative, this additional duty was stated to be Rs. 59,224/-. The State’s counsel, however, described the direction as recovery of Rs. 53,840/- as deficit stamp duty along with penalty of Rs. 5,384/-. In either case, the effect was a demand for extra duty more than seven years after registration.
Following this order, the Sub-Registrar issued a notice dated 23.5.2017 demanding Rs. 72,714/- from the petitioner towards deficit stamp duty, fine, validation fee and related amounts.
Aggrieved, the petitioner approached the Patna High Court in Civil Writ Jurisdiction Case No. 9294 of 2018. She asked for quashing of the order dated 27.4.2017 of Respondent No. 3 and the demand notice dated 23.5.2017 of Respondent No. 5.
The main plank of the petitioner’s argument was based on Section 47-A of the Indian Stamp Act, 1899, as amended for Bihar.
Her counsel submitted that under Section 47-A(1), a registering officer can make a reference to the Collector for determination of proper market value and stamp duty only at the time of registering the instrument, if he is satisfied that the classification or valuation is wrong or lower than the guideline value.
The petitioner argued that the Sub-Registrar registered the document on 10.10.2007 after accepting the stamp duty. He did not make any reference at that time. Making a reference in 2015, more than seven years later, was therefore beyond his powers and bad in law.
The petitioner further relied on Section 47-A(3). This provision allows the Collector to act on his own (suo motu) and examine a registered instrument that has not been referred to him under sub-section (1). However, this can be done only within two years from the date of registration.
As the registration was done in October 2007, the two-year window closed in October 2009. The petitioner argued that after expiry of this period, even the higher authority could not reopen the valuation or demand more stamp duty.
The relevant statutory text of Section 47-A(1) and 47-A(3) was reproduced in the judgment, making it clear that the power of the registering officer is linked to the time of registration, and the Collector’s suo motu power is limited to two years.
The petitioner’s counsel also referred to two earlier decisions of the Patna High Court on the same issue: a Division Bench judgment in The State of Bihar & Others vs. Smt. Tetra Devi, reported in 2018(2) PLJR 136, and a Single Bench judgment in Shahnaz Begam vs. The State of Bihar & Ors., reported in 2018(2) PLJR 293.
On the other side, the State’s counsel accepted that a complaint was filed on 25.4.2014 by one Pramod Singh before the Sub-Registrar. He stated that, based on this complaint, the Sub-Registrar held an enquiry, concluded that the land was residential, and then sent Reference No. 194 dated 21.2.2015 to the Assistant Inspector General.
He explained that Stamp Case No. 266/2014-2015 was initiated and, after giving the petitioner opportunity of hearing, the order dated 27.4.2017 was passed directing her to pay deficit stamp duty with penalty.
After hearing both sides, the Patna High Court examined the core legal question: whether such a reference and subsequent order for enhanced stamp duty could legally be made so many years after registration of the deed.
The Court observed that, from the materials on record, it was clear that a reference under Section 47(A)(1) regarding classification or valuation of property can be made only before registration of the document. The language of the provision makes this plain.
The Court held that this position was already settled by the earlier Patna High Court judgments in Shahnaz Begam and Tetra Devi. Those cases had clarified that the registering officer has no jurisdiction to refer a case under Section 47-A(1) after the deed is registered.
In the present case, the Sub-Registrar had made the reference more than seven years after registration. The Court found that he did so “without any authority or jurisdiction” and in a manner directly contrary to Section 47(A)(1).
Further, the Court emphasized that even the higher authority, Respondent No. 3, had no power under Section 47-A(3) to re-examine the correctness of the market value and duty payable after two years from the date of registration.
Since the deed was registered in October 2007, any suo motu review by the Collector or equivalent authority after October 2009 would be barred by the statute. Therefore, the action taken in 2015 and 2017 was outside the legal time limit.
On this reasoning, the Court held that the actions of both Respondent No. 3 and Respondent No. 5 were not only without jurisdiction but also arbitrary, perverse and illegal, being in clear violation of Section 47(A)(1) and (3) of the Indian Stamp Act, 1899.
As a result, the Court quashed the impugned order dated 27.4.2017 passed by Respondent No. 3 and the demand notice dated 23.5.2017 issued by Respondent No. 5. The respondents were restrained from proceeding further in the matter.
Accordingly, the writ petition was allowed, giving complete relief to the petitioner from the late demand of additional stamp duty, fine and related charges.
Why This Judgment Matters
This judgment is important for land buyers and sellers across Bihar, especially those who purchased land long ago and fear sudden demands for extra stamp duty.
The Patna High Court has made it clear that registration authorities cannot reopen old sale deeds at any time they wish. Their power to question valuation or classification is strictly limited by Section 47-A of the Indian Stamp Act, 1899.
For ordinary citizens, this means that once a sale deed is properly registered and the stamp duty is accepted, the matter should normally end there. If no action is taken within the fixed legal time, the authorities cannot come back years later demanding more money.
The decision also protects buyers from being harassed based on private complaints made after long delay. Even if someone complains, the registration officials must act within the powers and time limits given by law.
For lawyers and officials, the ruling reinforces that references under Section 47-A(1) must be made before registration, and any suo motu action under Section 47-A(3) must be taken within two years. Ignoring these limits will render the proceedings void.
Legal Issues and Answers
Issue: Can the Sub-Registrar make a reference under Section 47-A(1) of the Indian Stamp Act, 1899 to revalue a property and demand extra stamp duty more than seven years after the sale deed was registered?
Answer: No. The Patna High Court held that a reference under Section 47-A(1) can be made only before registration of the instrument. A reference made years after registration is without authority and contrary to the statute.
Issue: Can the higher registration authority or Collector, under Section 47-A(3), suo motu examine and enhance stamp duty after two years from the date of registration?
Answer: No. The Court held that the suo motu power under Section 47-A(3) is confined to two years from the date of registration. Any action taken beyond this period is illegal and without jurisdiction.
Issue: Are the orders demanding deficit stamp duty and penalty passed in 2017, based on a 2007 sale deed, valid?
Answer: No. As both the reference and the suo motu action were beyond the statutory powers and time limits, the Court quashed the order dated 27.4.2017 and the demand notice dated 23.5.2017 and barred further proceedings.
Cases Cited by the Court
- 2018(2) PLJR 136 – The State of Bihar & Others vs. Smt. Tetra Devi.
- 2018(2) PLJR 293 – Shahnaz Begam vs. The State of Bihar & Ors.
Case Details
Case Number: Civil Writ Jurisdiction Case No. 9294 of 2018
Case Title: Savitri Devi vs. The State of Bihar & Others
Citation: 2022 (4) PLJR 415
Court: High Court of Judicature at Patna
Coram: Hon’ble Mr. Justice Mohit Kumar Shah
Date of Judgment: 29.08.2022
Advocates for Petitioner: Mr. Akhileshwar Kumar Shrivastva, Advocate; Mr. Amrit Kirti, Advocate
Advocates for Respondents: Mr. Rewti Kant Raman, AC to SC-11; Mr. Pyush Kumar Pandey, Advocate
Nature of Case: Writ petition under civil writ jurisdiction challenging orders demanding deficit stamp duty and related charges.
Statutory Provision Involved: Section 47-A of the Indian Stamp Act, 1899 (as applicable in Bihar)
Link to Full Judgment: Click here to read the Patna High Court judgment
If you found this explanation helpful and wish to stay informed about
how legal developments may affect your rights in Bihar,
you may consider following Samvida Law Associates for more updates.